




As British holidaymakers seek practical ways to reduce holiday costs, traditional high-street banks continue quietly penalising overseas spending with non-sterling transaction fees averaging around 2.75% to 2.99% per transaction. For a family spending £2,000 abroad, that translates to losing roughly £60 in unavoidable bank charges just for tapping a standard debit card. Enter Currensea (visit official site →), an innovative UK travel card that bypasses foreign transaction fees without forcing you to switch your current account or open a whole new digital bank. Trusted by over 200,000 British travellers and saving users an estimated £13 million in collective banking fees, this independent Currensea review tests whether this card truly delivers effortless holiday savings compared to Revolut, Monzo, Wise, and Chase UK. Sending funds abroad or planning an international trip? Use our Money Transfer & FX Matcher ↓ to find the lowest-fee provider for your destination.
The ‘No-Switch’ Travel Card: How Currensea Connects to Your Bank
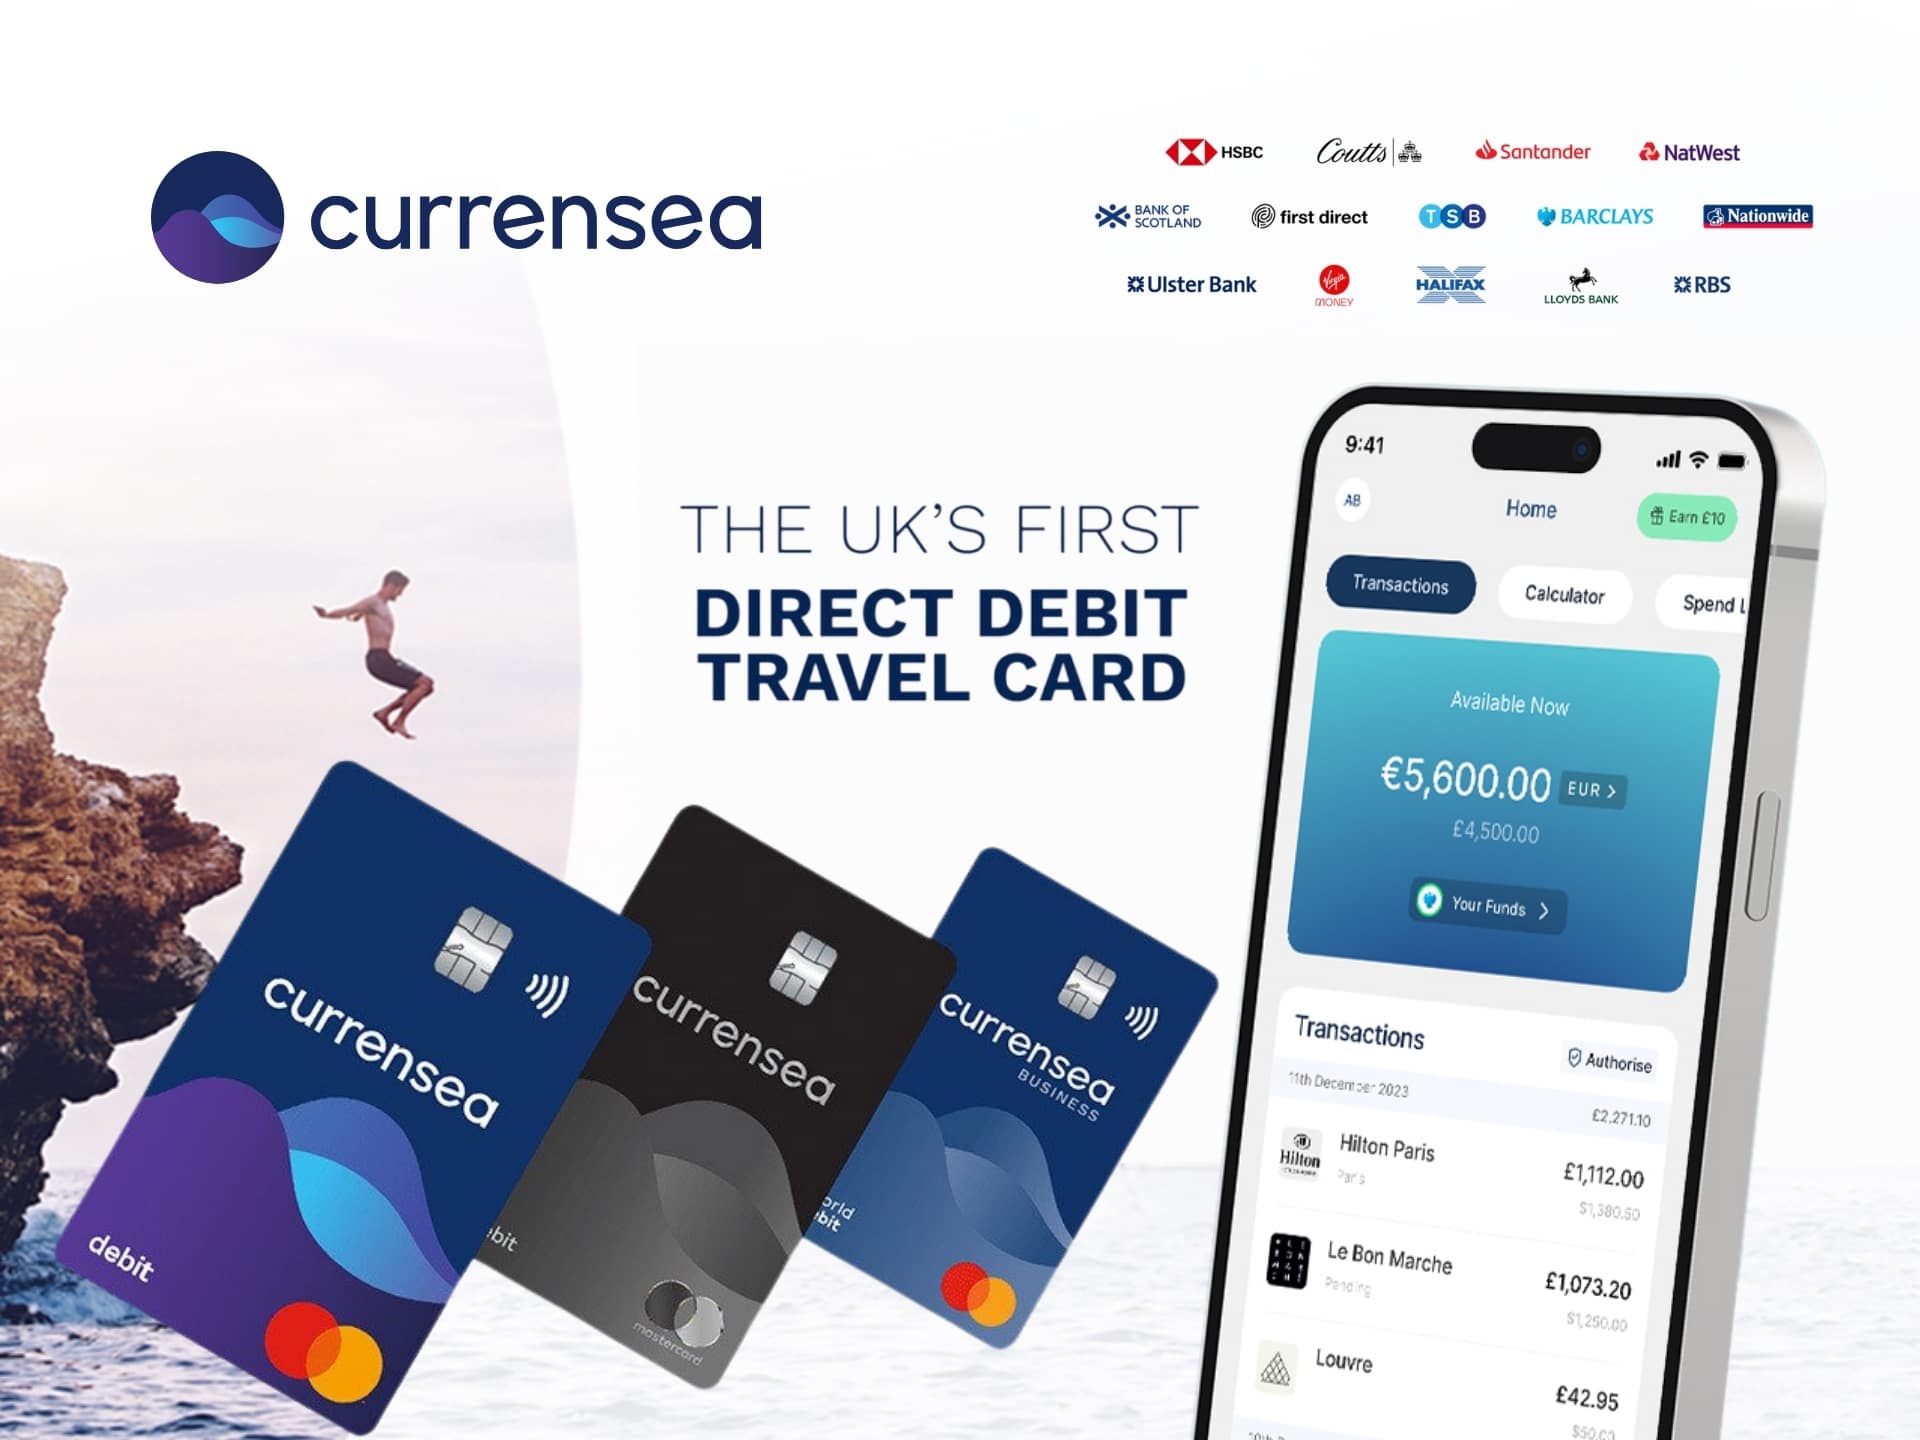
The defining innovation behind Currensea is that it is not a bank account, nor is it a prepaid card requiring manual pre-trip top-ups. Instead, Currensea operates as an authorised financial layer powered by UK Open Banking infrastructure. It issues you a contactless Mastercard debit card (available in physical plastic or digital form for Apple Pay and Google Wallet) that links directly to your existing high-street bank account.
How Open Banking Direct Debit Works in Practice
When you purchase a meal in Rome, hire a scooter in Bali, or book a train in Tokyo across any of its 180 supported currencies, the transaction flows seamlessly:
- Instant Overseas Payment: You tap your Currensea Mastercard abroad just like any standard payment card. The merchant charges your card in the local currency.
- Wholesale Interbank Conversion: Currensea converts the foreign currency into British Pounds using the live Mastercard wholesale interbank rate, plus a nominal 0.5% FX markup on the free plan (or 0% on premium plans).
- Automated Bank Collection: Rather than forcing you to transfer funds beforehand, Currensea automatically collects the exact GBP equivalent from your primary UK bank account (such as Barclays, HSBC, Lloyds, or NatWest) via an authorised Direct Debit.
This automated flow completely removes the cognitive overhead of holiday budgeting. You never experience the embarrassment of a declined transaction at a restaurant counter because you forgot to top up a secondary app, nor do you leave stranded foreign currency trapped in forgotten digital wallets after returning to the UK.
BudgetFitter Math: The Hidden 3% High-Street FX Trap
To demonstrate the real-world value proposition, consider what typical high-street banks levy on international card payments:
| Payment Card Provider | Overseas Non-Sterling Fee | Weekend Exchange Markup | Cost on £2,000 Holiday Spend | Typical Annual Saving |
|---|---|---|---|---|
| Major High-Street Banks (Barclays, HSBC, Lloyds, Santander) | 2.75% to 2.99% per transaction | Standard bank rate spread | Around ~£55 to ~£60 in fees | Baseline benchmark |
| Currensea (Essential Plan) | 0.50% markup above Mastercard rate | 0% (No weekend surcharge) | Around ~£10.00 in fees | Saves around ~£45 to ~£50 per holiday |
| Currensea (Pro & Elite Plans) | 0% (Pure wholesale interbank rate) | 0% (No weekend surcharge) | £0.00 in FX markups | Saves around ~£55 to ~£60+ per holiday |
By simply tapping a Currensea card instead of your everyday bank card, an average British family saves roughly 80% to 85% on exchange rates without altering their domestic banking arrangements.
Currensea: What’s the Catch? (And How Does It Make Money?)
Whenever a financial product promises massive savings without requiring you to switch accounts, savvy consumers naturally ask: what is the catch? At BudgetFitter, our editorial team scrutinises the fine print to uncover the exact commercial mechanics behind fintech tools. Here are the four legitimate caveats you must understand before signing up:
1. The 0.5% FX Markup on the Free Tier
While Currensea eliminates the punitive 2.99% fee charged by high-street banks, its free Essential plan is not completely fee-free. It adds a flat 0.5% exchange rate markup above the Mastercard wholesale rate. On £1,000 of overseas spending, this fee equals £5.00. While substantially cheaper than the ~£30.00 charged by traditional banks, digital accounts like Chase UK and Starling offer a true 0% markup. If you want a 0% rate with Currensea, you must upgrade to an annual paid tier.
2. Physical Card Delivery Fee
Setting up your account and using a virtual card via Apple Pay or Google Wallet is entirely free. However, if you order a physical plastic Mastercard for your wallet, Currensea charges a one-off delivery fee of around ~£4.95. This is a common practice among fintech providers to cover physical card manufacturing and Royal Mail postage.
3. Direct Debit Clearing Lag
Because Currensea pulls money from your primary current account via Direct Debit rather than a continuous payment authority, transactions do not appear on your high-street banking statement instantaneously. Transactions typically settle between one and three business days later. You must maintain sufficient funds in your linked current account to cover your holiday spending, preventing accidental overdraft fees from your main bank.
4. Overseas Cash Withdrawal Caps
While Currensea allows fee-free ATM cash withdrawals abroad up to ~£500 per calendar month on the Essential and Pro plans, any cash withdrawn beyond this threshold incurs a 1% fee (with a minimum charge of £1.00). If you travel to cash-dominated destinations and plan to make heavy ATM withdrawals, this limit warrants careful budgeting.
How Currensea Turns a Profit
Currensea operates a transparent business model that does not rely on selling customer data. It generates commercial revenue through three distinct streams:
- Foreign Exchange Spreads: The 0.5% markup collected on Essential plan international spending.
- Merchant Interchange Fees: Every time you tap your Mastercard abroad, the retailer pays a small interchange fee, a fraction of which is shared with Currensea.
- Premium Subscription Upgrades: Annual memberships from frequent flyers who opt for the paid Pro (~£25/year) and Elite (~£120/year) tiers for added travel perks.
Currensea Subscription Plans Compared: Essential vs Pro vs Elite
To cater to different travel frequencies, Currensea structures its membership into three tiers. Choosing the optimal tier depends entirely on your projected annual overseas spend:
| Feature & Benefit | Essential Plan | Pro Plan | Elite Plan |
|---|---|---|---|
| Annual Subscription | Free (£0/year) | From ~£25/year (or ~£2.50/mo) | From ~£120/year (or ~£10/mo) |
| Physical Card Fee | Around ~£4.95 one-off | Free delivery included | Free premium card included |
| FX Exchange Markup | 0.50% above Mastercard rate | 0% (True wholesale rate) | 0% (True wholesale rate) |
| Fee-Free ATM Withdrawals | Up to ~£500/month (then 1%) | Up to ~£500/month (then 1%) | Up to ~£750/month (then 1%) |
| Car Hire Discounts | Standard partner rates | 10% off at Hertz + free additional driver | 15% off at Hertz + free additional driver |
| Travel Connectivity | None included | Free travel eSIM credits | Free travel eSIM credits (up to 5 packages) |
| Luxury Travel Privileges | None | Preferred Hotels stay discounts | £100 luxury hotel credit + Ten Concierge |
The Break-Even Analysis: The 0.5% FX fee difference between Essential and Pro means that if you spend more than ~£5,000 abroad in a single year, the 0% rate on the Pro tier completely offsets the ~£25 annual cost. When factoring in the free additional driver perk on Hertz car hire (which typically costs £10 to £15 per day when booked directly) and complimentary travel eSIM data, frequent holidaymakers can achieve substantial net savings by selecting Pro.
Is Currensea Safe? Open Banking vs FSCS Protection Explained
When connecting any third-party card to your primary bank account, security is paramount. Currensea adheres to strict UK financial compliance standards:
FCA Regulation
Currensea Limited is authorised and regulated by the Financial Conduct Authority (FCA) under the Payment Services Regulations 2017 as an Authorised Payment Institution (Firm Reference Number: 843507). It complies with stringent UK data protection laws and payment security frameworks.
The FSCS Deposit Protection Nuance
A frequent question among travellers is whether Currensea provides Financial Services Compensation Scheme (FSCS) protection. The answer lies in how the service handles your funds:
- Currensea is not a bank and does not hold user deposits.
- Your savings and salary remain permanently inside your primary UK high-street bank account (such as Barclays, Lloyds, or NatWest).
- Because your money never leaves your primary bank until the split second you make a purchase, your funds enjoy full £85,000 FSCS deposit protection under your existing banking institution.
This structure eliminates the counterparty risk associated with holding large balances inside uninsured digital wallets or unregulated travel money cards.
Transaction Security & Chargeback Rights
Currensea connects via secure Open Banking APIs using cryptographic bank-grade encryption. The company never sees or stores your online banking login credentials or security passwords. Furthermore, because the card operates on the global Mastercard network, your overseas purchases are protected by standard Mastercard Chargeback rights, offering valuable dispute protection if an overseas airline, hotel, or merchant fails to deliver agreed services.
Currensea vs Revolut, Wise, Monzo, Starling & Chase UK
To see how Currensea stacks up against popular travel finance apps, review our side-by-side comparison:
| Provider | Account Architecture | FX Rate / Fee Structure | Weekend Foreign Exchange Surcharge | Best Suited For |
|---|---|---|---|---|
| Currensea | Linked Debit Card Layer | 0.5% (Essential) or 0% (Pro/Elite) | None (0% surcharge 24/7) | Zero-switch convenience without top-ups |
| Revolut | Digital Prepaid Account | 0% up to limit, then 1% fee | 1.0% weekend surcharge | App-based budgeting & multi-feature tools |
| Wise | Multi-Currency Account | Mid-market rate + fee from ~0.43% | None (transparent fixed fee) | Holding & sending 40+ global currencies |
| Monzo / Starling | Full UK Bank Account | 0% (Mastercard wholesale rate) | None (0% surcharge 24/7) | Complete primary bank switching |
| Chase UK | Full Digital Bank Account | 0% Mastercard rate + 1% cashback | None (0% surcharge 24/7) | Maximising travel cashback & ATM access |
Currensea vs Revolut: No Preloading vs Multi-Feature Banking
Revolut is a feature-packed digital banking application, but for straightforward travel spending, it carries two notable friction points. First, Revolut is a prepaid account requiring manual top-ups; if your balance runs out mid-meal, your card declines until you open the app and transfer money. Second, Revolut imposes a 1.0% weekend exchange rate surcharge when foreign currency markets are closed. Currensea eliminates both issues: it never requires manual preloading, and it never applies weekend exchange penalties.
Currensea vs Wise: Frictionless Overlay vs Multi-Currency Vault
Wise is the gold standard for expatriates, international freelancers, and global travellers who need to hold balances in dozens of currencies simultaneously or receive international wire transfers with local account details. However, using Wise for a brief family holiday requires calculating your budget in advance, transferring GBP, and converting funds into Euros or Dollars inside the app. If you simply want your holiday spending deducted directly from your everyday current account, Currensea offers a distinctly more seamless experience.
Currensea vs Starling Bank: The No-Switch Layer vs Dedicated Travel Account
For British travellers comparing modern fintech options, the decision frequently narrows to Currensea versus Starling Bank. Both leverage the Mastercard network to deliver massive savings over traditional high-street banks, but they approach travel finance from fundamentally different angles:
- Account Opening Friction: Starling is a fully licensed UK bank, meaning opening an account requires downloading a separate app, providing photo identification, undergoing electronic credit and identity checks, and managing a separate account number and sort code. Currensea is a lightweight ‘overlay’ debit card that links directly to your existing Barclays, HSBC, Lloyds, or NatWest account via Open Banking in under two minutes—requiring zero credit checks and zero account switching.
- Foreign Exchange Fees (%0 vs 0.50%): Starling applies a true 0% markup over the Mastercard wholesale exchange rate on all overseas debit card transactions. Currensea’s free Essential plan applies a modest 0.50% markup (dropping to 0% on paid Pro and Elite plans). On a £1,000 holiday spend, Starling charges £0 in FX fees while Currensea Essential charges £5.00—a minor difference that most holidaymakers happily trade for the convenience of not managing a separate bank.
- Overseas Cash & ATM Withdrawals: Starling allows up to £300 daily in free overseas ATM cash withdrawals with no monthly percentage surcharge. Currensea allows up to £500 per month fee-free on the Essential tier, but applies a 1% to 2% surcharge on cash withdrawals beyond that monthly ceiling.
- FSCS Deposit Protection: Starling holds your deposits directly under its own £85,000 Financial Services Compensation Scheme (FSCS) bank licence. Currensea does not hold customer funds; your money stays in your primary UK bank account until drawn via Direct Debit, meaning your deposits remain continuously protected by your host bank’s £85,000 FSCS guarantee.
Currensea vs Monzo & Chase UK: Everyday Banking vs Surgical FX Layer
Both Monzo and Chase UK represent popular digital alternatives for holidaymakers. Chase provides a true 0% FX rate alongside 1% cashback on debit card spending for your first year, while Monzo offers comprehensive budgeting pots. However, like Starling, both require establishing an entirely new current account and juggling manual bank transfers before every trip. If you have decades of direct debits, salary credits, and mortgage ties with an established high-street institution and prefer not to open an additional current account, Currensea functions as a surgical, plug-and-play solution.
For more detailed app comparisons across flights, accommodation, and currency management, read our complete guide to the top travel eSIMs for overseas data.
The Insider Connection: Hilton Honours Debit Card
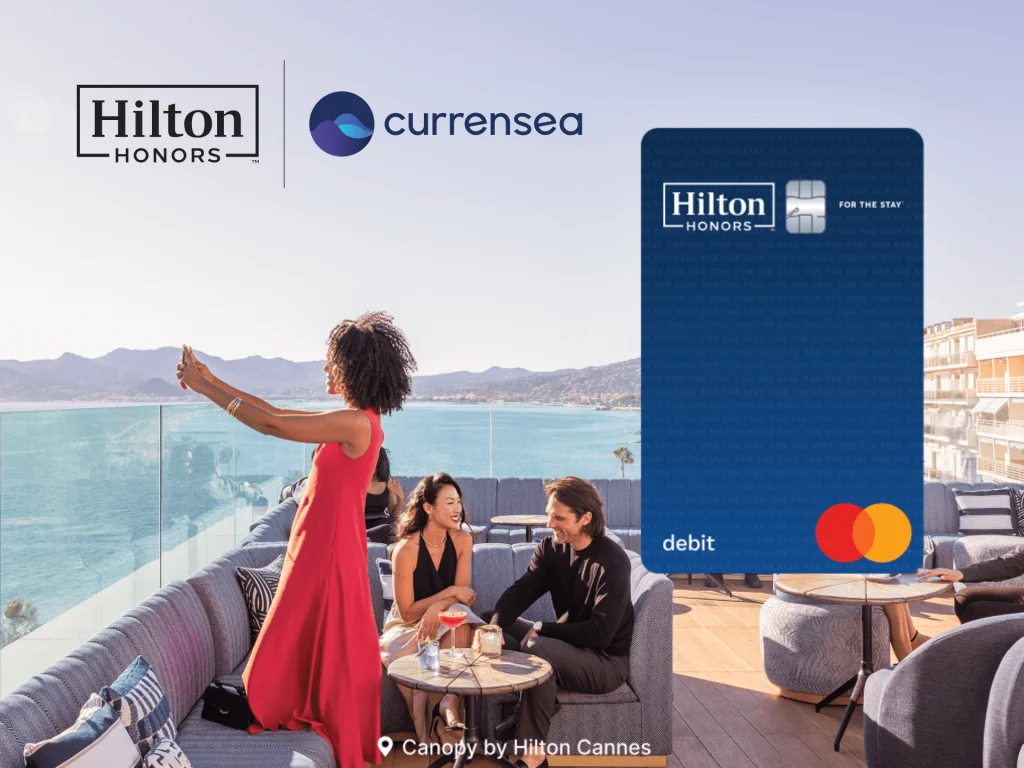
An impressive demonstration of Currensea’s technological pedigree is its institutional adoption by major international brands. In the UK, the Hilton Honours Debit Card is powered entirely by Currensea’s Open Banking infrastructure. This card allows travel rewards enthusiasts to collect Hilton Honours points on every pound spent internationally, while leveraging the exact same automated Direct Debit mechanism that draws money directly from their linked current account. To evaluate whether collecting hotel loyalty points offsets card membership fees, explore our detailed analysis of Hilton Honors points value and redemption math.
Currensea Pros & Cons: The Complete Travel Card Breakdown
To help UK holidaymakers and business travellers decide whether ordering a Currensea card aligns with their financial habits, BudgetFitter has audited its key benefits against its primary operational limitations:
The Advantages of Currensea
- Zero Account Switching Required: Connects seamlessly to your existing UK current account (Barclays, HSBC, Lloyds, NatWest, Santander, and more) via Open Banking, eliminating the friction of opening a new bank or passing credit checks.
- No Preloading or Stranded Foreign Balances: Spends directly from your main bank account in pounds sterling with automatic live conversion, removing the risk of leftover foreign currency trapped in digital wallets after your trip.
- Massive Savings Over High-Street Banks: Replaces standard 2.99% high-street bank foreign transaction fees with a modest 0.50% markup on the free Essential tier, slashing foreign spending overheads by over 80%.
- No Weekend Exchange Rate Surcharges: Unlike Revolut which imposes a 1% markup on foreign currency conversions executed during weekends, Currensea passes through wholesale Mastercard rates with zero weekend penalty fees.
- FCA Authorised & Host-Bank FSCS Protection: Operates as an FCA-authorised Payment Institution, with all your deposited funds remaining safely protected by your primary UK bank’s £85,000 FSCS guarantee.
- Hilton Honors Debit Card Partnership: Offers the UK’s first points-earning travel debit card, allowing frequent hotel guests to earn Hilton Honors loyalty points on everyday domestic and overseas spending.
The Drawbacks & Limitations of Currensea
- 0.50% FX Markup on Free Tier: While drastically cheaper than traditional banks, it is not 100% fee-free like Starling Bank or Chase UK, which offer true 0% Mastercard wholesale FX rates.
- One-Off Physical Card Delivery Fee: Ordering a physical debit card incurs a modest one-time postage and packaging charge of around ~£5.95, though virtual cards on Apple Pay and Google Pay are instant and completely free.
- Direct Debit Settlement Lag: Transactions take 1 to 2 business days to clear against your linked bank account via Direct Debit, requiring you to ensure sufficient funds remain in your current account.
- Overseas ATM Cash Withdrawal Limits: Free ATM withdrawals are capped at £500 per month on the Essential tier, with a 1% to 2% surcharge applied beyond the free monthly ceiling.
- Cannot Hold Foreign Currency Balances: Unlike Wise or Revolut multi-currency accounts, you cannot lock in exchange rates ahead of travel or hold balances in foreign currencies.
- No Section 75 Credit Protection: Because Currensea is a debit card linked via Direct Debit rather than a credit card, overseas spending does not build your UK credit score or offer Section 75 Consumer Credit Act protection.
For families planning European holidays, using Currensea to eliminate card fees on hotel bookings, park tickets, and dining is a proven strategy outlined in our Disneyland Paris budget guide. Furthermore, to avoid high-street network roaming charges while spending abroad, pair your travel card with low-cost connectivity from our guide to the 5 most searched travel eSIMs in the UK, and save on airport or cross-country rail connections via our Seatfrog UK review.
Interactive Matcher
Find the Lowest-Fee International Money Transfer Service
Select your destination currency, transfer volume, and priority speed. Our engine compares wholesale interbank spreads and transfer fees across verified UK fintechs.
Final Verdict: Should You Order a Currensea Card?
Currensea successfully solves the single most frustrating aspect of UK holiday spending: the lazy, extortionate foreign exchange markups imposed by traditional high-street banks. By cleverly harnessing Open Banking Direct Debit technology, it delivers 80% to 85% fee savings without requiring you to switch accounts, complete credit applications, or juggle prepaid balances.
While power users willing to open a new digital bank account can secure a true 0% rate with Chase UK or Starling, Currensea remains the undisputed champion of low-friction travel finance. For UK travellers who value convenience, seamless bank integration, and reliable overseas savings, ordering the Currensea Mastercard is an exceptionally smart budget decision before your next trip abroad.



Leave a Comment
Join the community discussion
Sign in to share verified discount codes, report expired deals, or connect with fellow smart savers.
No comments yet. Be the first!
Be the first to share an active discount code, referral link, or shopping experience with our community.